

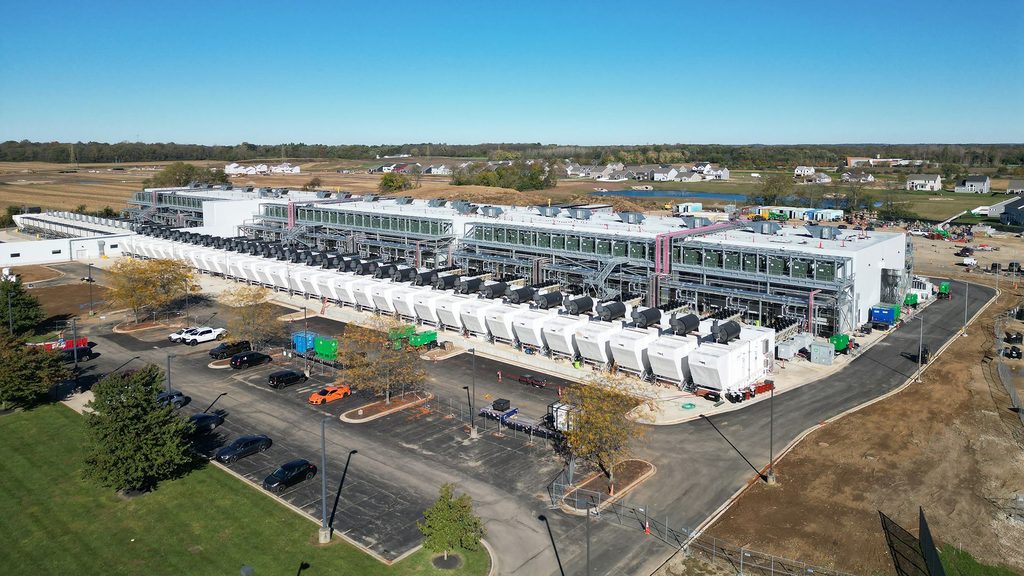
The boom in AI infrastructure in the United States, estimated at $10,000 billion, is running up against a growing realization: according to new estimates, 65% of planned data center projects in the United States may not be feasible in practice, raising fresh concerns about an investment frenzy that is increasingly being compared to a financial bubble. According to a survey published by the Financial Times on October 18, analysts at Bernstein estimate that only 35% of proposed data center projects in the country are credible, while at least 47 major projects have already been delayed, withdrawn, or blocked as of 2026. More than 1,000 U.S. municipalities have also lobbied for restrictions on new facilities, reflecting growing resistance to the facilities’ enormous electricity needs, water consumption, and potential financial consequences for local residents. These findings cast doubt on the sector’s ability to build the IT infrastructure needed for its ambitious expansion plans, with projections suggesting that U.S. investments could exceed $10,000 billion between 2025 and 2032. These revelations come as AI-related stocks are experiencing sharp declines, corporate borrowing costs are rising, and investors are beginning to question whether the sector’s extraordinary spending commitments can generate sufficient returns.
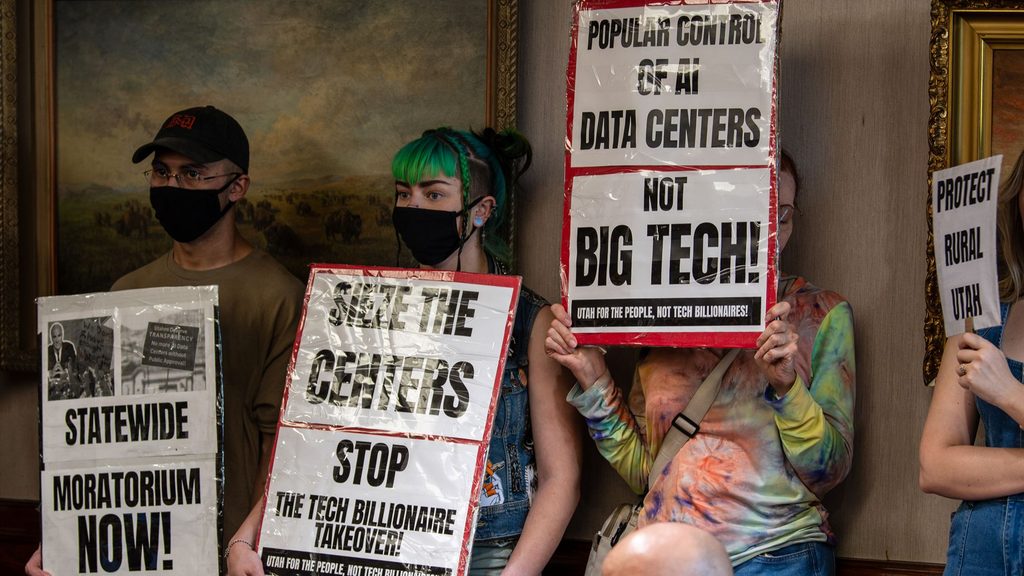
These challenges extend far beyond the financial markets, as plans for AI facilities are increasingly meeting resistance from communities concerned about environmental damage, rising energy bills, and the allocation of public resources to some of the world’s wealthiest technology companies. Across the United States, local governments are facing disputes over zoning permits, tax incentives, and the significant demands that data centers place on already strained power grids. In several regions, residents have organized opposition campaigns or called for temporary construction restrictions, while developers face long wait times for grid connections and shortages of specialized equipment, including transformers and state-of-the-art cooling systems. These obstacles can delay projects by several years, driving up construction costs and complicating agreements with customers who expect computing capacity to be available on fixed schedules. Findings from the Financial Times suggest that the gap between announced projects and what can actually be built is becoming one of the industry’s most significant challenges. Even projects with substantial financial backing may face uncertain timelines if utilities cannot guarantee the necessary electricity supply. For investors, this creates a troubling prospect: billions of dollars could remain tied up in infrastructure unable to generate revenue by the originally planned dates.
$35 billion in debt
The growing uncertainty surrounding AI infrastructure has also highlighted the financial vulnerabilities of companies that rely heavily on debt to finance their rapid expansion, with CoreWeave emerging as one of the warning signs most closely watched by Wall Street. The Nvidia-backed cloud computing provider experienced a sharp sell-off in both its stock and corporate bonds during the week of October 12, as investors reassessed the risks associated with its massive construction commitments and the growing burden of its debt. Yields on some CoreWeave bonds climbed to nearly 16%, compared with borrowing rates below 10% when these securities were initially issued, reflecting a substantial deterioration in investor confidence. The company had approximately $35 billion in debt as of the end of June, in addition to several billion more in lease-related obligations, while continuing to invest heavily in facilities for AI developers. Although CoreWeave has a full order book and has defended the strength of its business model, analysts warn that costly refinancing could jeopardize its profitability if customer payments fail to keep pace with capital requirements. This turmoil has spread beyond CoreWeave, intensifying scrutiny of other emerging cloud providers and raising broader questions about the ability of debt-fueled AI expansion to withstand a prolonged period of high interest rates.
These growing challenges are now affecting some of the industry’s most ambitious projects, including OpenAI’s Stargate initiative and Microsoft’s rapidly expanding network of AI data centers. Stargate, touted as a massive infrastructure investment involving OpenAI, Oracle, and SoftBank, has raised questions about its financing, construction timelines, and the coordination needed to deliver the promised computing capacity. Although its backers continue to pursue this expansion, these difficulties demonstrate just how vulnerable even projects backed by major tech companies remain to delays and rising costs. Meanwhile, Microsoft has pulled out of a major data center project involving Nscale in Loughton, Essex, after uncertainties regarding electricity availability threatened to push back the facility’s commissioning until the 2030s. This decision, announced on October 18, highlights an increasingly significant obstacle to the expansion of the AI sector: access to a reliable power supply cannot necessarily keep pace with the rate at which companies are announcing new investments. Microsoft continues to seek other infrastructure partnerships, but this abandoned deal underscores the growing gap between financial commitments and the actual ability to bring operational data centers online.
These infrastructure setbacks are part of a broader reassessment of AI investments on Wall Street, where investors have begun to question whether the sector’s unprecedented spending can be justified by future revenues. During the week ending October 16, tech stocks suffered substantial losses, with the Philadelphia Semiconductor Index falling by about 10% according to some sources, as concerns intensified over excessive valuations and debt-fueled expansion. This sell-off affected companies across the entire AI supply chain, including semiconductor manufacturers, cloud infrastructure providers, and companies dependent on the continued construction of new data centers. At the heart of the debate lies the growing gap between the colossal amounts of capital committed to AI infrastructure and the revenue needed to sustain these investments over the long term. Major tech companies have committed to investing hundreds of billions of dollars in new facilities, cutting-edge processors, and highly power-intensive computing operations, even as questions remain about how quickly AI services will generate sustainable profits. Investors are also scrutinizing long-term leases, financing structures, and the potential consequences of delays that could push back expected revenue while interest expenses continue to mount. Although demand for AI computing remains strong, recent market turbulence suggests that investors are increasingly reluctant to assume that every announced expansion will translate into profitable operations.
An Investment Boom
The next major test for the AI infrastructure boom in the United States will be whether the sector’s largest companies can demonstrate that their exceptional capital expenditures are generating measurable financial returns, rather than simply expanding their capacity at a faster pace than demand warrants. The upcoming financial reports from Microsoft, Amazon, Alphabet, and Meta are expected to draw particular attention, as investors scrutinize capital expenditures, cloud computing revenues, operating margins, and the rising costs associated with supporting AI services. Analysts will also be watching to see if developers begin to postpone the construction of additional facilities, renegotiate contracts, or focus their investments on projects with guaranteed power supplies and established customer bases. A slowdown would not necessarily mean that AI technology itself has failed, since demand for computing power could continue to grow even if some infrastructure projects become financially or technically unfeasible. However, the combination of expensive borrowing, overburdened power grids, local opposition, and uncertain returns increases the risk that the sector’s expansion will fall significantly short of initial forecasts. For an investment boom based on seemingly unlimited growth prospects, the increasingly thorny question is no longer simply how much infrastructure companies are willing to finance, but rather what can actually be built, operated, and made profitable.
The AI Boom Faces a Reality Check 10,000G$ Later: 65% of Data Centers Are Being Questioned


